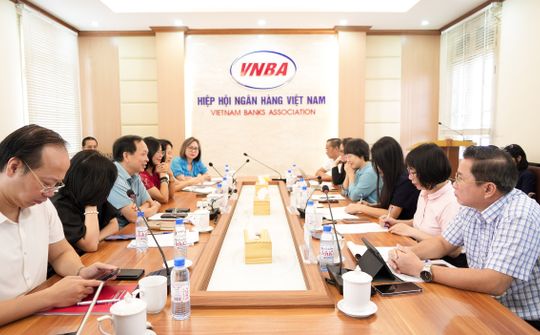
The meeting was co-chaired by Dr. Nguyen Quoc Hung, Vice Chairman cum Secretary General of VNBA and Mr. Mai Van Phan, Deputy Director General of the Department of Land Management (under MONRE).
Participants also included Mr. Phạm Thanh Ngọc, Deputy Director of the Legal Department of SBV; Ms. Phạm Thị Thịnh, Head of the Department of Surveying and Land Registration, Department of Land Management; Ms. Tran Minh Tam, Deputy Head of the Vietnam Banks Legal Club (under VNBA); representatives from the Civil and Economic Law Department of the Ministry of Justice; and VNBA member banks attending both in-person and online.
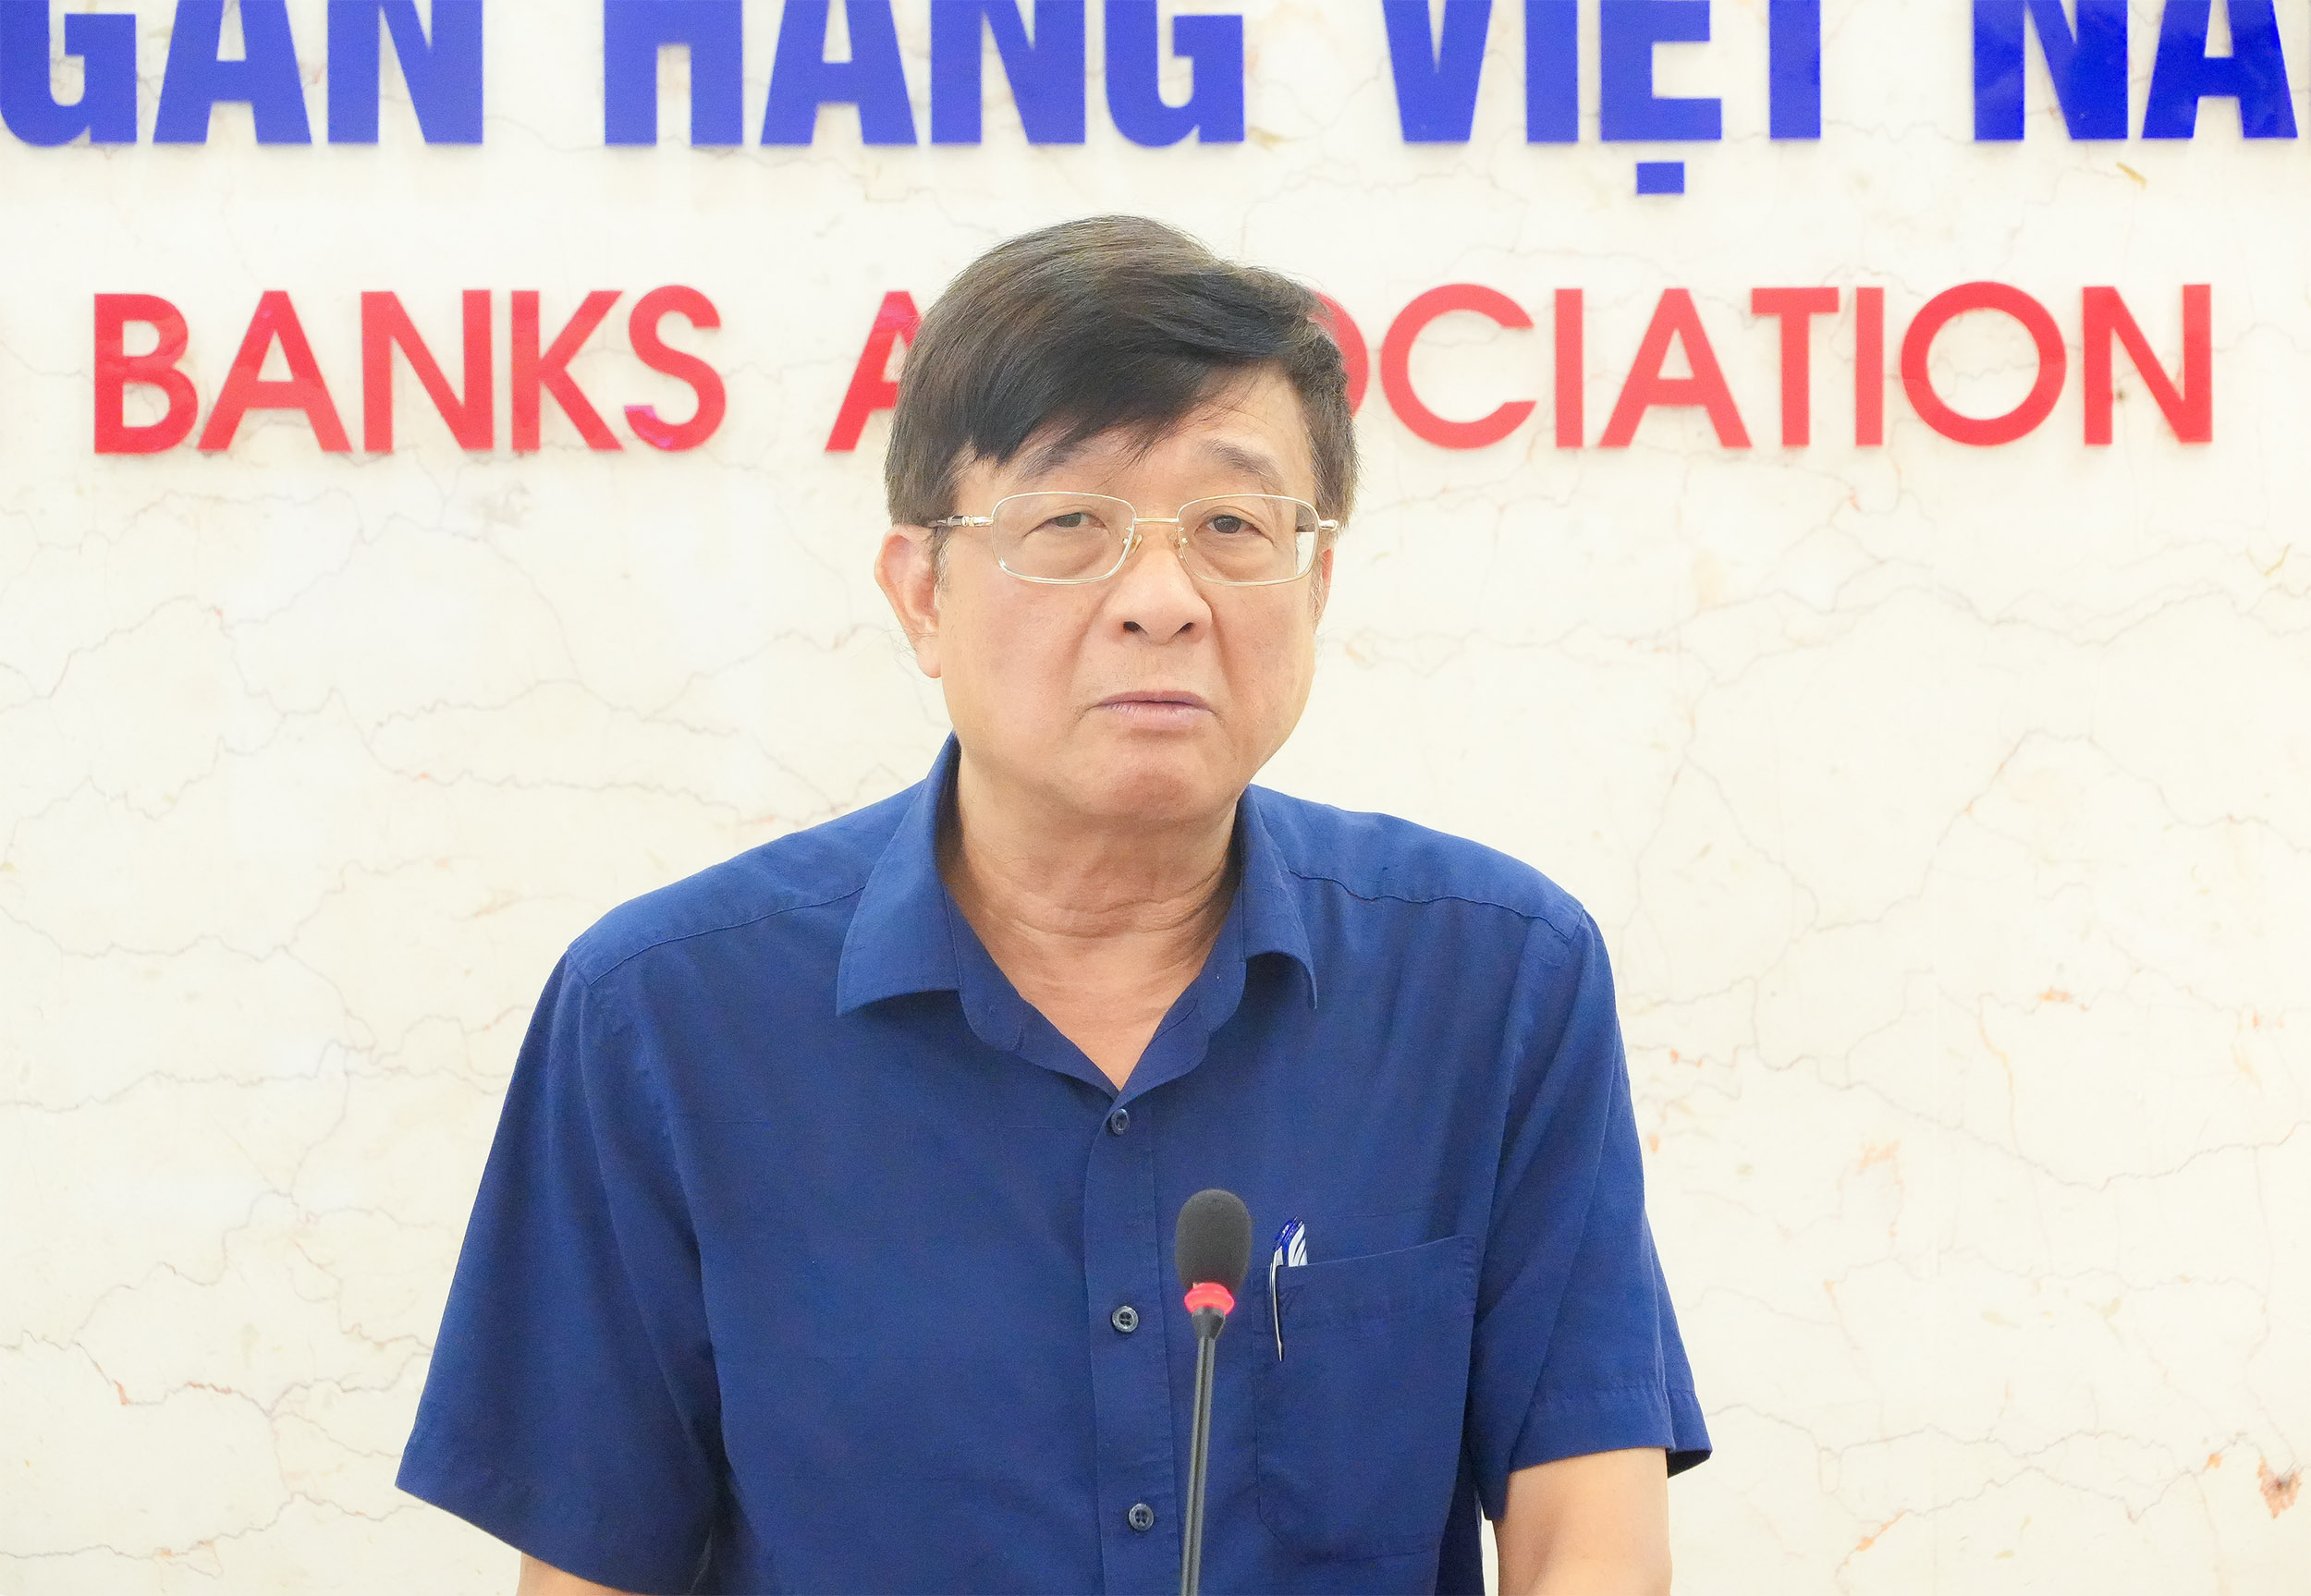
Dr. Nguyen Quoc Hung, Vice Chairman cum Secretary General of VNBA
In the opening remarks, Dr. Nguyen Quoc Hung noted that VNBA had received numerous reports from credit institutions highlighting difficulties in receiving and holding collateral assets as a substitute for repayment obligations—particularly real estate acquired through non-performing loan (NPL) resolution. The purpose of the meeting, he said, was to foster discussion, build consensus, and formulate recommendations from the banking sector to relevant regulatory bodies to address these barriers.
Dr. Hung called for candid, constructive contributions grounded in practical challenges, with the aim of identifying more effective solutions to improve the NPL resolution process. He also encouraged member institutions to continue providing feedback for collective improvement.
At the meeting, Ms. Tran Thi Minh Tam, Deputy Head of the Vietnam Banking Legal Club presented a summary of current challenges in handling bad debts, especially in the receipt and retention of secured assets, most notably real estate. These issues have been compiled from practical experiences shared by VNBA member organizations.
According to Ms. Tam, current laws do not clearly define what constitutes “holding real estate as a result of bad debt handling,” nor do they clearly specify the rights and obligations of credit institutions regarding mortgaged assets and the mortgagor. Various cases are governed by different regulations, leading to difficulties in resolving disputes and exercising the rights of credit institutions. Although legal provisions (Clause 3, Article 139 of the 2024 Law on Credit Institutions and Article 179 of the Civil Code) mention the holding of real estate by credit institutions, there remains ambiguity regarding their ability to transfer ownership or register asset changes—except in the case where they have not accounted for the asset’s value or made depreciation entries, which is clarified in Decree 135.
In practice, cases have arisen where the mortgagor has transferred real estate collateral to the credit institution or its asset management company (AMC) for debt resolution. However, when the asset appreciates in value, the mortgagor may deliberately create disputes to reclaim the property. Such conflicts hinder the management and disposal of assets by the credit institution.
Ms. Tam further noted that if the credit institution does not register the ownership transfer of the collateral, it cannot independently sell the asset. Upon expiration of the holding period, the institution must then auction the property, triggering additional procedures, prolonging the resolution timeline, and limiting the institution’s autonomy.
Additionally, Decree No. 35/2025/NĐ-CP stipulates that credit institutions cannot record the value of held assets on-balance-sheet nor reduce the borrower’s debt. This results in overdue debt obligations continuing to accrue, despite the borrower legally transferring the collateral to the institution via an agreement or enforcement decision. This adversely affects the legal rights of both credit institutions and borrowers and creates risks of potential lawsuits from the borrower for damages, even though the asset transfer was lawful.
Furthermore, the law does not clearly define whether credit institutions may use or exploit the real estate they hold, leading to inefficiencies in utilizing land use rights and attached assets during the holding period.
Regarding the issue of accepting secured assets in lieu of debt repayment, Ms. Tam emphasized that this is a necessary mechanism that helps credit institutions resolve bad debts quickly and reduce costs by avoiding complex litigation procedures. However, in practice, this process has faced difficulties due to inconsistencies in interpretation and implementation among local land registration offices, which have imposed requirements that credit institutions are unable to fulfill.
She cited examples where some Departments of Natural Resources and Environment (DoNREs) required credit institutions to obtain approval from the provincial People's Committee for receiving land use rights under Point c, Clause 3, Article 127 of the 2024 Land Law and Clause 5, Article 60 of Decree 102/2024/NĐ-CP dated July 29, 2024. However, these scenarios do not involve land use rights acquisition for investment projects promoting socio-economic development. In other cases, DoNREs have required a change of land use purpose before agreeing to register the transfer of property ownership to the credit institution—adding time and procedural complexity and affecting the rights of both the credit institution and mortgagor.
In cases where credit institutions receive collateral from the enforcement agency (as per Clause 2, Article 104 of the Law on Civil Judgment Enforcement) to offset enforced debt amounts, failure to register the ownership transfer means the institution cannot sell the property directly and must resort to public auctions. This is despite the fact that many of these properties have already been auctioned multiple times without success. "If credit institutions must repeat the auction procedures again, it would be extremely time-consuming, costly, and largely ineffective in practice" she stated.
During the meeting, representatives from credit institutions further raised issues from their own operations, including: regulations on debt assignment; receiving assets in lieu of debt repayment per legal obligations; accounting for debt reduction when receiving collateral; and procedures for transferring collateral ownership.
A representative from VIB emphasized that credit institutions should have the right to transfer assets and register land ownership changes to ensure legality and reduce legal risks. VIB also proposed that competent authorities issue clear guidelines on exercising these rights.
Meanwhile, a representative from ACB suggested that the use of collateral should not be mandatory and called for detailed guidance on timelines for asset resolution. ACB also proposed introducing regulations on the acceptable ratio of fixed asset value used to offset debts, helping to maintain financial stability.
All participating credit institutions agreed on the need for clearer and more flexible guidelines on secured asset handling and ownership transfer to support effective debt recovery.
Dr. Hung expressed his hope that the meeting would encourage open, constructive, and practical discussions, leading to solutions that improve bad debt resolution efficiency. He also encouraged member credit institutions to continue contributing ideas to help identify more effective solutions.
Credit institutions are currently facing challenges in both holding real estate from debt resolution and accepting secured assets in lieu of debt repayment.
VNBA Puts Forward Policy Recommendations
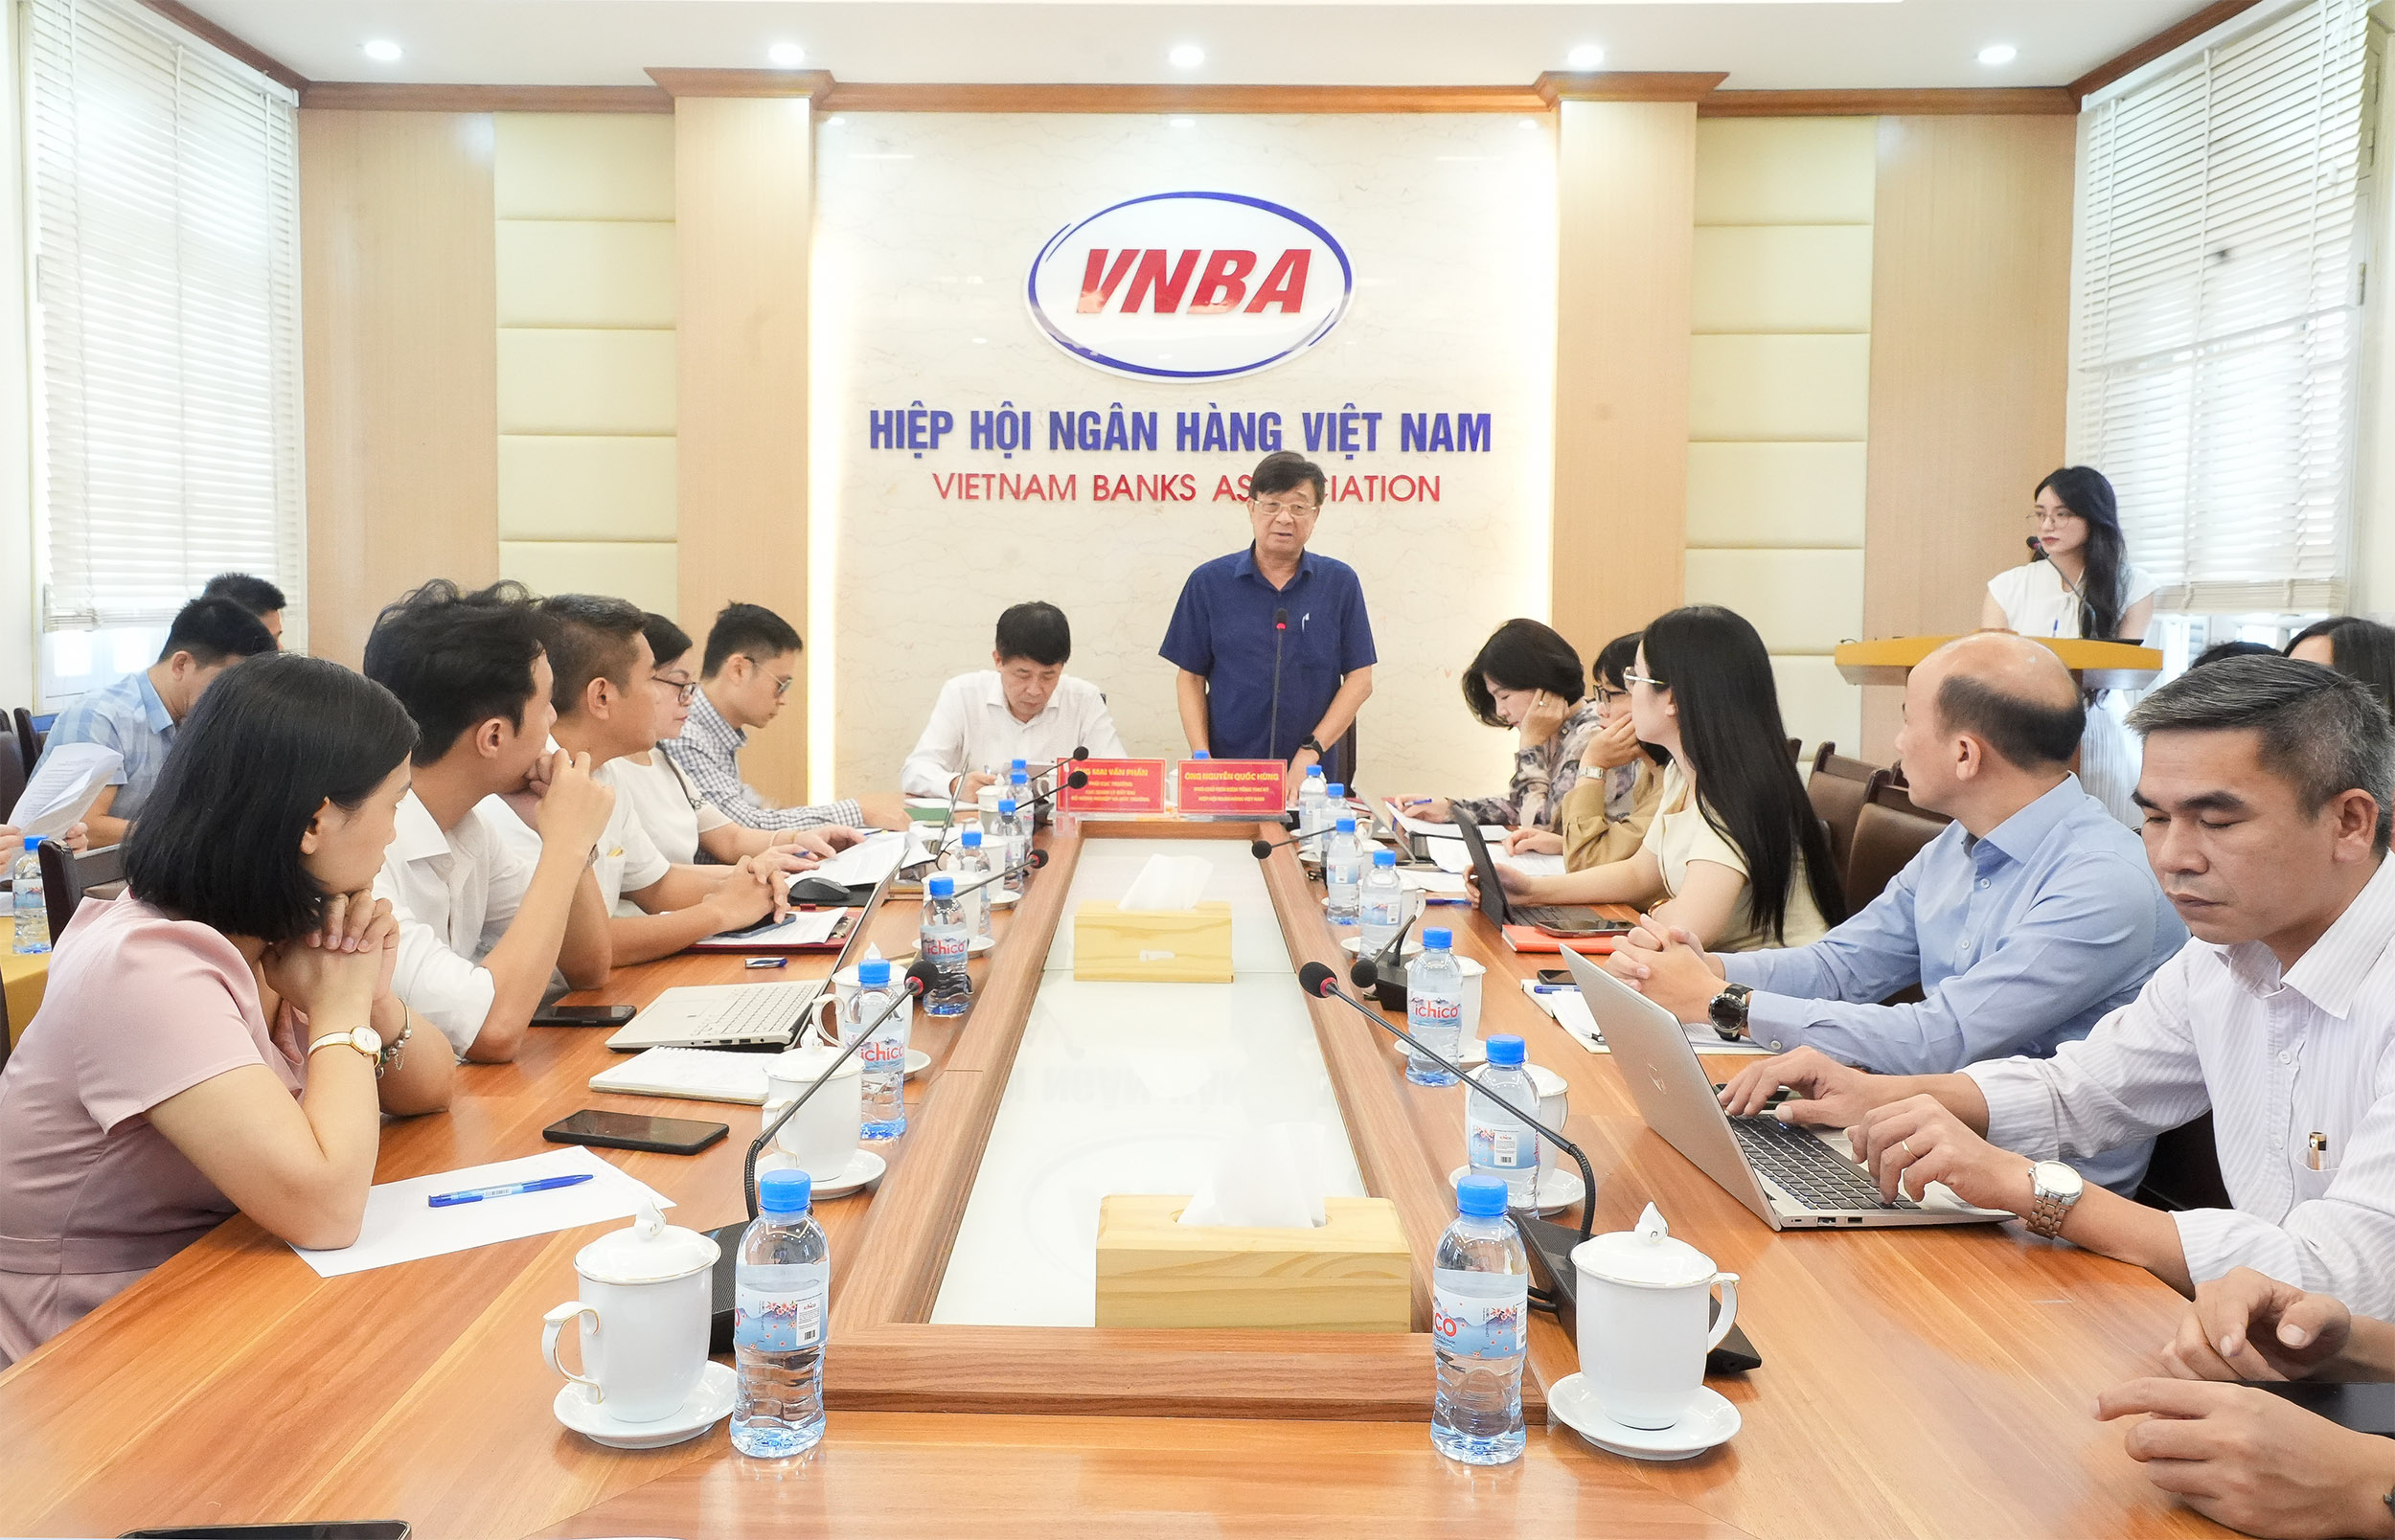
Overview of meeting
To address the aforementioned difficulties, regarding current regulations on the holding of real estate due to debt resolution, VNBA recommends that SBV coordinate with the MONRE and other relevant ministries and agencies to issue clear definitions of “holding real estate” under Clause 3, Article 139 of the Law on Credit Institutions (LCIs), and to clarify the rights of credit institutions during the period of asset holding.
VNBA proposes allowing credit institutions to account for such assets as debt offset, enabling them to reduce borrowers’ obligations without being required to register ownership or land use rights transfers. Simultaneously, regulations or guidelines should be issued to allow for the registration of changes in land and asset status, recognizing the credit institution’s holding of the property for debt resolution purposes, without requiring land use purpose conversions or investment approvals—as would typically be necessary for land use right transfers.
In cases where credit institutions dispose of secured assets during or after the holding period, they should be allowed to sell the property directly, even if the certificate of land use and ownership of attached assets still names the mortgagor as the legal owner.
Regarding regulations on accepting secured assets in lieu of debt repayment, VNBA recommends that MONRE and the Ministry of Justice issue regulations or guidelines for land and asset registration procedures in such cases. These should remove the requirement for prior approval from the provincial People’s Committee for the transfer of land use rights.
If legally permissible, land use conversion procedures and ownership transfer registrations should be processed concurrently. In addition, credit institutions should be allowed to register ownership or transfer real estate acquired through enforcement proceedings either directly to themselves or to a buyer, as stipulated in secured agreements.
In response to these issues and VNBA’s recommendations, representatives from regulatory agencies, including the Legal Department of the SBV, the Department of Civil and Economic Law (Ministry of Justice), and the Department of Land Management, provided clarification and feedback.
Mr. Phạm Thanh Ngọc, Deputy Director of Legal Department (SBV), noted that the revised Law on Credit Institutions would facilitate credit institutions in handling secured assets, especially with explicit provisions regarding asset seizure rights.
He added that the Government is actively pushing for legal reforms to address bottlenecks. The SBV’s Legal Department is currently reviewing areas related to digital transformation and financial investment. For the specific issues discussed at the meeting, the department will gather input and submit recommendations to competent authorities. It also requested that VNBA compile credit institutions’ proposals for submission to the SBV, which will, within its jurisdiction, provide specific guidance to help resolve these difficulties.
Mr. Mai Van Phan, Deputy Director General of the Department of Land Management
At the meeting, Mr. Mai Van Phan, Deputy Director General of the Department of Land Management (MONRE), provided responses to individual issues. He emphasized the need for clear regulations to ensure consistency in implementation.
Regarding entities involved with real estate—such as land and attached assets linked to bad debts or mortgaged properties not yet released—Mr. Phan explained there are two fundamental mechanisms for debt recovery and asset utilization: transfer via sale or auction, and credit institutions acquiring and using the assets directly by paying for them, in line with Article 144 of the Law on Credit Institutions.
He also stressed the need to clarify definitions for debt offset, asset holding, and transfer of rights, as well as clearly define the start of the five-year period stipulated in Clause 3, Article 139 concerning the holding of real estate for debt resolution purposes—and how it should be handled upon expiration.
Regarding transfer pricing, he noted that the asset value at the time of mortgage is often lower than at the time of resolution, thus clear guidance is needed to address such valuation discrepancies.
The Deputy Director General also proposed that the Department of Civil and Economic Law (Ministry of Justice), MONRE, and the SBV jointly examine issues related to transfer agreements between credit institutions and land change registration. He stressed the importance of coordination among government agencies to unblock resources and support credit institutions in the near future.
In closing remarks, Dr. Nguyen Quoc Hung highly appreciated the valuable, constructive, and practical contributions made during the meeting. He affirmed that the VNBA will compile all issues and proposals raised by credit institutions and submit them to MONRE, the Ministry of Justice, and the SBV for joint resolution. This aims to facilitate bad debt recovery and enhance the effectiveness of secured asset handling in the banking sector.
T.Đ
VNBA News