Vietnam is at a pivotal moment in its development journey. With one of Southeast Asia’s fastest-growing digital economies, the country is well-positioned to harness technology for sustainable growth.
One particularly powerful growth lever is collaboration between fintech firms and traditional banks. These partnerships blend the agility, data-driven innovation, and reach of fintechs with the capital base, compliance infrastructure, and trust of banks. Together, they can accelerate inclusive finance and support green investment.

Fintech expert Rahn Wood
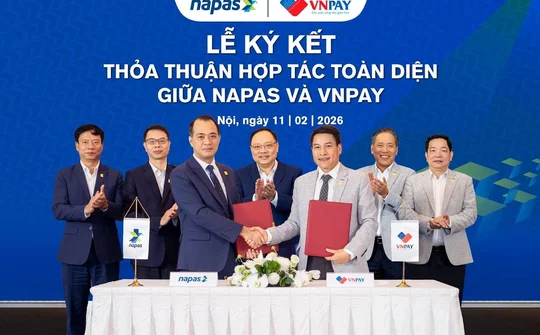
This acceleration in the transformation of financial services is in no small way due to some pivotal fintech-bank partnerships such as VNPay, which enables the mobile banking apps of many institutions, and Payoo, which facilitates repayments for many financial institutions.
With the imminent impact of AI on many traditional industries and activities, middle income countries such as Vietnam face significant opportunities and challenges. In addition, the task of managing personal and business cashflows and controlling expenses can be made more accessible.
Protecting customers from risks such as increasingly ubiquitous scams and fraud may also be enhanced through the combination of traditional players and fintech’s respective strengths.
Vietnam has a formal national action plan aligning 17 of the United Nations’ Sustainable Development Goals (SDGs) to 115 Vietnamese targets which all can, to some extent, be improved through greater fintech-bank partnering. However, such collaborations can significantly help Vietnam achieve top SDG priorities such as SDG8 (Decent Work and Economic Growth) and SDG13 (Climate Action), whilst also addressing the systemic challenges.
In terms of SDG8, Vietnam’s small- and medium-sized enterprises (SMEs) form the backbone of its economy, contributing more than 40 per cent of GDP and employing the majority of the workforce. Yet, SMEs face a significant financing gap, estimated at over $21 billion. Banks often see such businesses as risky due to insufficient collateral, opaque financial records, and a lack of credit histories.
This is where fintechs can shift the paradigm. By leveraging alternative data such as mobile and QR payments, e-commerce sales and supply-chain records, fintech platforms can build more accurate and nuanced credit scores including self-employed citizens. When integrated with bank lending and financial education, this approach reduces risk and widens access.
A concrete example could be a digital SME lending platform: fintechs provide the scoring algorithms and customer onboarding, whereas banks provide the capital and compliance oversight: the result being faster, more inclusive lending.
As for SDG13, Vietnam is among the most climate-vulnerable countries in the world. With the government pledging to achieve net-zero emissions by 2050, financing this transition requires innovative financial models.
Fintech-bank partnerships can enable green financing at scale. One promising business model is pay-as-you-go rooftop solar loans. Here, fintechs can partner with suppliers to integrate Internet of Things monitoring devices with mobile wallet or account-based repayments, ensuring that households or SMEs pay for solar installations in small, affordable increments. Banks or managed funds, in turn, could provide the long-term, wholesale financing and risk management.
This approach can reduce default risk, expand access to clean energy and open up syndicated investment opportunities in green energy. Beyond rooftop solar, similar fintech-bank models could finance electric mobility, energy-efficient appliances, or climate-resilient agriculture. The impact: measurable carbon dioxide emissions avoided, renewable megawatts installed, and greater resilience to climate change.
Successful collaborations
Over the past decade, there have been a number of successful large-scale fintech-bank partnerships. In more recent years, neobanks like Cake, Timo, and TNEX have led the way in user-centric digital financial services operating under the sponsorship of their respective bank licensees.
Perhaps the most promising new wave of fintech-bank partnerships is just beginning in the form of international fintech partnerships such as Liobank digital bank between Fintech Farm (UK parent) and OCB, which has attracted hundreds of thousands of new customers. International fintechs such as Circle Asia Technologies can bring best practice and move more quickly than traditional banks or finance companies to deliver personalised payment solutions for customers that align to their needs and financial capacity.
While the opportunities are clear, several challenges must be addressed for these partnerships to scale sustainably. These cut across regulatory, tech, market, operational, and financial dimensions.
Vietnam’s fintech sandbox and licensing frameworks are gradually evolving, but questions remain about further scope for digital lending, e-money, digital investment products and open banking. Strict e-verification and anti-money laundering rules also make it challenging to onboard rural or under-documented populations. Moreover, Vietnam’s green finance taxonomy is not yet finalised, creating uncertainty.
Data remains fragmented across institutions, with limited API standards and access. Credit-scoring models that rely on alternative data are yet to be proven or approved at national scale, whilst cybersecurity and data privacy are growing concerns as more consumers become more digitally dependent.
Low digital literacy, especially among rural or peri-urban populations, women, and older citizens, constrains adoption. Cultural and gender biases persist within lending practices and on the climate front, households and SMEs may not yet prioritise rooftop solar or electric vehicles unless paired with incentives or subsidies.
Banks and fintechs often operate with different cultures: banks are compliance-driven and risk-averse, whereas fintechs thrive on experimentation and speed. Without aligned incentives, partnerships can stall. Distribution remains a challenge too, as last-mile agent networks are thin in remote areas, especially where the role of community and state-managed organisations are strongest.
Vietnamese banks face high capital costs and rely heavily on short-term deposits, making it difficult to finance long-tenor green projects without a deeper debt-capital market. Risk appetite mismatches also persist: banks remain overly cautious about lending to SMEs or women entrepreneurs without collateral, with the result that previous pilots reliant on donor subsidies have struggled to scale once support ends.
Pathways forward
To unlock the full potential of fintech-bank collaborations for SDG impact, financial inclusion, and competitiveness, Vietnam needs a coordinated strategy that addresses systemic barriers. Finalising the green finance taxonomy will provide guidance for sustainable investments, while expanding the fintech sandbox to cover digital lending, e-money, digital card issuance, and open banking frameworks creates an environment for experimenting with future fintech business models.
Promoting interoperability through open APIs and encouraging responsible data-sharing between fintechs and banks will enhance collaboration and operational efficiency across the sector. At the same time, leveraging concessional capital, donor guarantees, and risk-sharing mechanisms from financiers such as International Finance Corporation or Asian Development Bank can help de-risk green and SME lending, making funding more accessible and secure.
Building financial literacy among underserved groups, particularly women and rural communities, remains essential. Education programmes and user-friendly apps can make financial services more accessible and empower these populations to participate fully in the digital economy. Strengthening fraud prevention, ensuring transparent pricing, and providing grievance redress mechanisms will foster long-term trust in digital finance and protect end-users.
Finally, Vietnam can use tax incentives and other supportive measures to encourage business models in which fintechs contribute reach and data insights, banks provide capital and compliance expertise, and both parties share in the benefits of sustainable growth.
Vietnam’s journey towards the SDGs is both urgent and ambitious. By 2030, the country aims to foster inclusive economic growth, advance gender equality, and mitigate climate risks while transitioning to a low-carbon economy. Fintech-bank collaborations offer a powerful pathway to make this a reality: whether through bridging financing gaps, scaling climate-friendly investments, or empowering women entrepreneurs, these partnerships can unlock transformative impact.
Within the current global context of unpredictability and complexity, Vietnam should consider a whole-of-government effort covering finance, banking, trade, education, energy, and industrial regulations to create better conditions for fintech-bank partnerships. This will allow Vietnam to compete successfully, with other emerging markets in Southeast Asia such as Thailand, the Philippines, and Malaysia for talent, investment capital, and jobs of the future.
With targeted reforms, blended finance, and strong consumer protections, fintechs and banks can co-create solutions that deliver inclusive, green, and resilient growth. Together, they can help Vietnam achieve its SDGs – sustainably, inclusively, and at scale.