Regarding the issue of credit access for the real estate market, Governor Nguyen Thi Hong said that investment in the real estate sector has the characteristics of large investment capital with long terms. Therefore, real estate investment capital needs to be mobilized from many channels, and capital from banks is only one of them. According to current legal regulations, credit institutions (CIs) will decide on granting credit based on agreements with customers on loan amounts, terms, and interest rates.
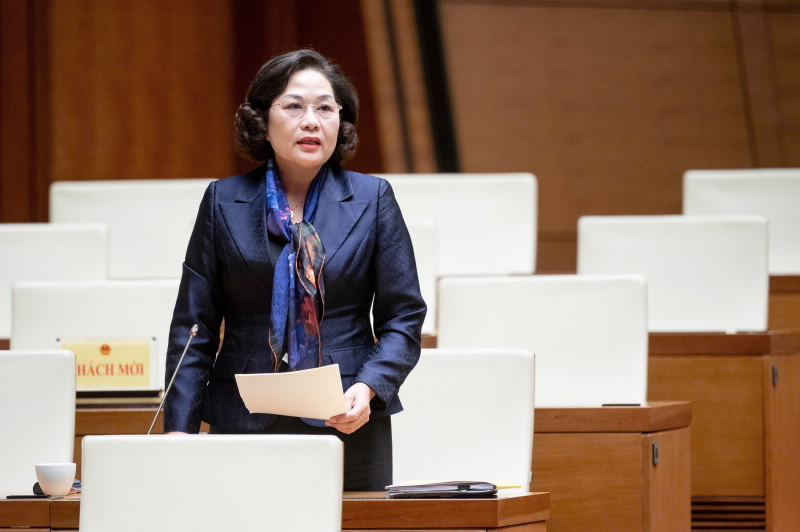
SBV Governor Nguyen Thi Hong
In particular, unlike normal businesses, CIs, in addition to operating according to their own business purposes, must always ensure safety ratios according to the regulations of the State Bank and must ensure capital recovery to be ready to pay depositors, otherwise it may cause consequences for the CIs themselves as well as for the safety of the system and the economy.
Therefore, even if there are feasible projects with the ability to repay debts, commercial banks may still refuse to lend because the loan term of this project may not be suitable for the bank's capital balance; or because the bank prioritizes other more urgent goals to ensure the safety of the banking system. However, in reality, credit in the real estate sector has increased rapidly in recent times and real estate credit growth is often higher than the general growth rate of the economy. Currently, the total outstanding real estate credit is up to 3.15 million billion VND, accounting for over 20% of the total outstanding debt of the economy.
Regarding the assessment of high interest rates, the Governor said that borrowing businesses always want low interest rates and if compared to the wishes of businesses, the assessment that interest rates are still high is always correct and understandable.
However, the Governor hopes that the National Assembly will share and acknowledge the efforts and achievements that the State Bank and credit institutions have achieved in the recent past. Specifically, in the context of very high international interest rates in the past, Vietnam's interest rate level has been controlled and lending interest rates have only decreased by about 3% since the beginning of 2022. When businesses and people are in difficulty, credit institutions also spend their own financial resources to waive and reduce interest rates and fees for businesses and people and it is estimated that this figure is up to 60 trillion VND - this is not a small number.
According to the Governor of the State Bank, real estate loans with long terms often have higher interest rates than short-term loans. Because long-term deposits also have higher interest rates than short-term deposits. In its management direction, the State Bank always directs credit institutions to save operating costs to continue reducing lending rates, supporting businesses and people. Along with that, it strengthens the simplification of administrative procedures to save time, creating favorable conditions for businesses and people to access credit capital in general, and real estate credit in particular.
Regarding social housing credit, the Monitoring Report has shown that the real estate market is currently experiencing an imbalance and especially the social housing segment is still limited. In fact, the Government is very determined to direct agencies, ministries and branches to focus on solutions to develop social housing and even call for socialization to build and eliminate temporary and dilapidated houses. However, to achieve the goal of developing social housing, it still depends a lot on the financial resources of the State.
Currently, the banking sector has a number of social housing lending programs such as: Lending under Decree 100 through state-owned commercial banks and the Bank for Social Policies; Housing lending programs for poor households and policy beneficiaries through the Bank for Social Policies; Lending to poor households to build flood-proof houses in the Central region; Lending to build residential clusters in flooded areas of the Mekong Delta and the Central Highlands; Lending to support residential land under the National Target Program on socio-economic development of ethnic minorities and mountainous areas.
According to the Governor of the State Bank, the capital for lending to social housing programs is currently limited and in principle, social policy housing is supported by the state budget. In the past, in the context that the state budget has not been allocated much, in response to the Program aiming for 1 million social housing apartments by 2030, the banking sector has launched a package of 120 trillion VND and to date this package has increased to 145 trillion VND. This is the capital mobilized by credit institutions from the people and credit institutions use their own financial resources to reduce lending interest rates from 1.5 to 2%/year for borrowers (for investors within 3 years and for borrowers within 5 years). However, the disbursement of the credit package has not been much (1,700 billion VND) because this is the first stage of implementing this Program and people are still facing difficulties so the demand for capital is not high. The Governor hopes that in the coming time, capital demand will increase and more disbursements will be made.
The Governor agrees with the opinions of some National Assembly deputies on using state budget resources to support social housing and needs to conduct a survey on the demand for home ownership and rental housing to find appropriate solutions.
VNBA News/SBV