Against a backdrop of continued global uncertainty, these measures contributed to macroeconomic stability, inflation control and improved access to bank financing for production, business activities and key growth drivers of the economy.
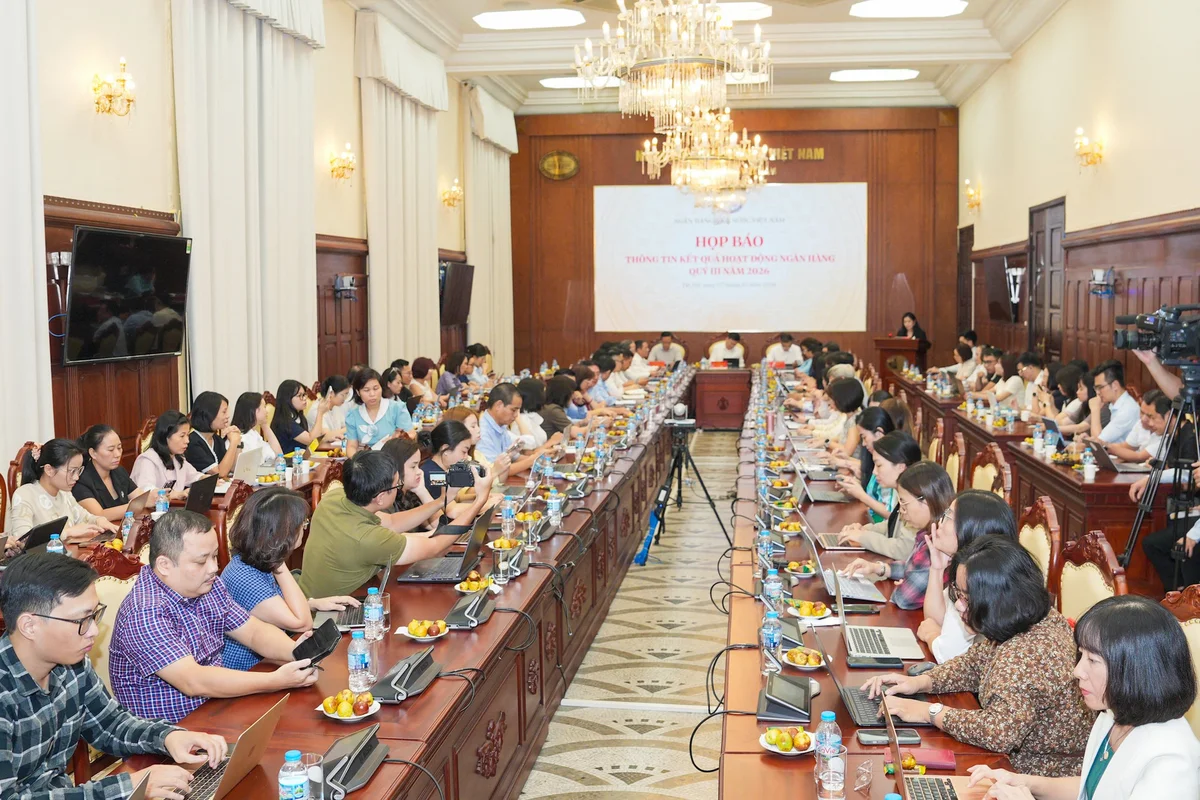
As of September 30, 2026, outstanding credit to the economy stood at approximately VND 20.75 quadrillion, up 11.59% from the end of 2025 and 16.69% year on year. The figures indicate that bank credit continued to play an important role in supplying capital to the economy during the first nine months of the year.
Proactive and flexible monetary policy management
During the first nine months of the year, the State Bank of Vietnam (SBV) continued to pursue a proactive and flexible monetary policy stance, closely coordinating with fiscal policy and other macroeconomic policies. The key objective was to strike an appropriate balance between inflation control, macroeconomic stability, orderly money-market conditions and support for economic growth.
Amid continued global uncertainty and Vietnam’s high degree of economic openness, the SBV flexibly deployed monetary policy instruments, including open-market operations, helping maintain system liquidity and ensure the smooth functioning of credit institutions.
Exchange-rate management remained flexible and responsive to domestic and international market developments. This helped the economy absorb external shocks, maintain stability in the foreign-exchange market and ensure that legitimate foreign-currency demand was met in a timely manner.
With regard to interest rates, the SBV implemented measures to stabilize market rates and facilitate access to credit for businesses and households. According to information presented at the SBV’s October 7, 2026 press briefing, the average deposit rate for newly arising transactions stood at 6.38% per year as of September 20, 1.15 percentage points higher than at the end of 2025.
Credit remained a key source of financing for the economy
One of the most notable developments in banking operations during the first nine months was the relatively strong expansion of credit. By September 30, total outstanding credit across the banking system had reached approximately VND 20.75 quadrillion, representing an 11.59% increase from the end of 2025 and a 16.69% increase year on year.
The SBV continued to direct credit toward production and business activities, priority sectors and emerging growth drivers. The credit-growth allocation mechanism was implemented with greater transparency and at an early stage, while providing additional room for credit institutions to meet financing needs in sectors considered important to economic growth.
Notably, additional credit extended to social housing, industrial parks and export-processing zones, major tourism and resort projects, and certain key projects with regional linkages was accommodated under the credit-management framework. This was intended to facilitate capital flows into sectors capable of generating broader economic spillovers.
Specialized credit programs also continued to be implemented and expanded. These included the VND 185 trillion credit program for the forestry and fisheries sectors; a lending program supporting value-chain linkages for high-quality rice production in the Mekong Delta; and credit programs for social housing, infrastructure investment and digital transformation.
Small and medium-sized enterprises (SMEs) also remained a priority. Under the relevant lending program, preferential interest rates are at least 1 percentage point per year below ordinary lending rates.
Credit allocation remained focused on productive sectors
The credit structure during the first nine months broadly followed the orientations set by the Government, the Prime Minister and the SBV, while remaining relatively consistent with the structure of the wider economy.
According to published data, as of the end of August 2026, credit to agriculture, forestry and fisheries accounted for approximately 6.08% of total outstanding credit, while industry and construction accounted for 23.1%, and trade and services for 70.11%.
Notably, approximately 77.44% of outstanding credit to the economy was allocated to production and business activities. This indicates that bank financing continued to play an important role in supporting business operations, investment and aggregate demand.
At the same time, rapid credit expansion has increased the importance of maintaining credit quality and managing risks. Further credit growth therefore needs to remain closely linked to the economy’s capacity to absorb capital, the efficiency of capital utilization and the risk-management capacity of individual credit institutions.
Cashless payments and digital banking continued to expand
Alongside credit growth, digital transformation remained another major feature of banking operations during the first nine months of 2026.
The SBV continued to improve the regulatory and policy framework for cashless payments, digital banking and the security and safety of payment activities.
Banking technology infrastructure continued to be upgraded and expanded. Digital banking products and services increasingly incorporated artificial intelligence, big data and automation to strengthen management capabilities, improve service quality, prevent fraud and develop modern banking products.
Most basic banking services are now available through digital channels, while many credit institutions have reported digital transaction rates above 95%. Digital lending has also continued to develop, helping streamline processes and making access to bank financing more convenient for customers.
The implementation of Project 06, the national initiative on population data, electronic identification and authentication, also continued to advance. As of October 2, 2026, the banking sector had reportedly completed biometric verification for more than 178 million customer profiles using chip-based citizen identity cards or VNeID, equivalent to 100% of accounts generating transactions through digital channels.
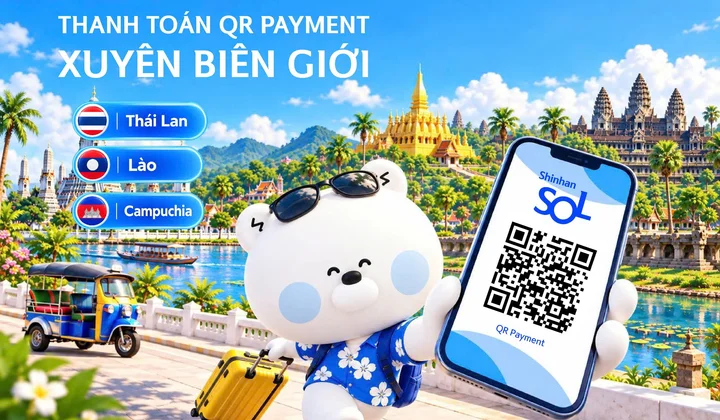
The SBV has also continued to expand cross-border retail payment connectivity through QR codes. Vietnam has established bilateral retail-payment connections with Thailand, Laos, Cambodia, China, South Korea and Singapore, while work is continuing on connections with other countries.
Strengthening fraud prevention and system security
Rapid digitalization has made cybersecurity, operational safety and fraud prevention increasingly important priorities for the banking sector.
The Information System for Supporting Customer Management, Supervision and Risk Prevention (SIMO) has continued to be deployed. According to the information presented at the press briefing, the system had collected reports from 150 institutions and shared information with 21 participating users. Its alerts had been issued for more than 5.6 million customer cases, while more than 1.9 million transactions had been suspended or cancelled, with a combined value exceeding VND 6.3 trillion.
These results demonstrate that digital transformation in banking is no longer limited to expanding online transaction channels. It is increasingly integrated with data governance, customer authentication, fraud prevention and risk management.
Banking sector priorities for the final months of 2026
During the final months of 2026, the SBV is expected to continue pursuing a proactive and flexible monetary policy stance, closely coordinating with fiscal policy and other macroeconomic policies to control inflation, maintain macroeconomic stability and support economic growth.
The SBV will continue to operate open-market operations in line with market conditions and monetary policy objectives, while providing timely liquidity support to credit institutions when necessary.
Interest-rate policy will continue to respond to developments in the macroeconomy, inflation and the money market. The SBV will closely monitor deposit and lending rates across the banking system, as well as credit growth and credit quality.
With regard to the exchange rate, the SBV will continue to closely monitor domestic and international developments and maintain flexible exchange-rate management, while coordinating monetary policy instruments to support foreign-exchange market stability.
The banking sector will also continue to accelerate digital transformation, strengthen sectoral databases, reform administrative procedures, expand online public services and cashless payments, and enhance measures to ensure cybersecurity and operational resilience.
Credit institutions will be expected to further improve operational quality, governance and risk-management capabilities while strictly complying with applicable regulations and directives issued by the Government and the SBV.
Overall, banking operations during the first nine months of 2026 reflected a relatively balanced combination of growth support and financial stability. Credit continued to expand at a relatively strong pace, with funding increasingly directed toward production, business activities and priority sectors. At the same time, digital transformation, cashless payments and fraud-prevention measures continued to strengthen the foundations for the modernization of Vietnam’s banking system.
As the economy pursues ambitious growth targets, the challenge for the banking sector is no longer simply to sustain credit expansion. It is equally important to preserve credit quality, contain financial risks, maintain an appropriate interest-rate environment and strengthen system-wide resilience. These factors will be critical in determining the banking sector’s contribution to economic growth in the fourth quarter and for the full year of 2026.
VNBA News