
The discussions focused on four key areas: narrowing the remaining gaps in access to and use of financial services; developing payment infrastructure and merchant acceptance points while strengthening connectivity among service providers; leveraging payment data to support cash-flow management and broaden access to financial services; and strengthening public confidence through enhanced safety, security, data protection, and digital financial literacy.
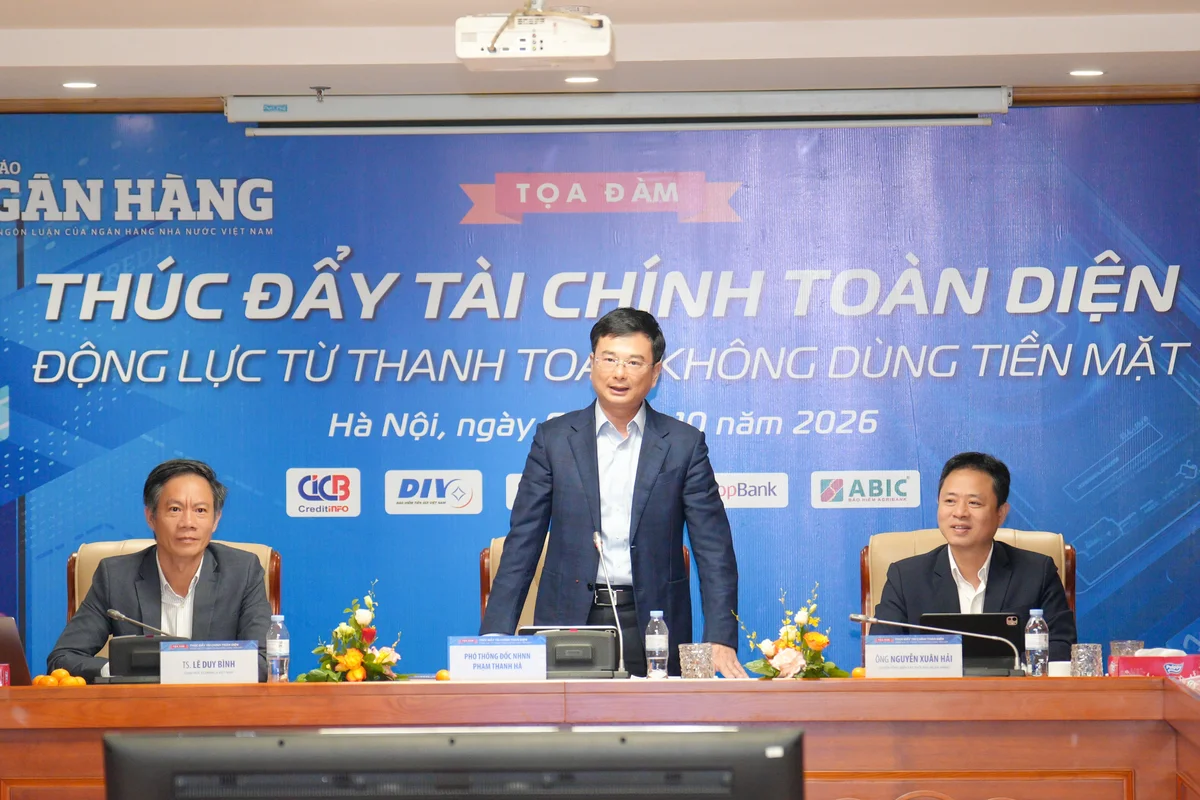
SBV Deputy Governor Pham Thanh Ha
The discussions highlighted the important role of cashless payments in expanding access to formal financial services. Greater adoption of digital payments can enable individuals and businesses—particularly underserved groups—to access and use financial services more regularly, conveniently and securely.
Aligning cashless payments with financial inclusion
In his concluding remarks, Deputy Governor Pham Thanh Ha stressed that the development of cashless payments must remain closely aligned with Vietnam’s National Financial Inclusion Strategy for 2026–2030, with a focus on ensuring that individuals and businesses have substantive, safe and effective access to financial services.
To achieve the objectives set out in the strategy, Deputy Governor Ha identified several priorities.
First, the regulatory and policy framework for payments and digital finance should continue to be refined in a consistent and transparent manner, creating an enabling environment for innovation and fair competition while safeguarding system security, users’ legitimate rights and the requirements of the digital economy.
Second, payment infrastructure and digital financial infrastructure should be developed in a coordinated manner, with stronger domestic interoperability and readiness for cross-border retail payment connectivity. Connectivity between banks and fintech companies should also be strengthened, with financial services increasingly embedded into integrated digital ecosystems such as healthcare, education and public services.
Third, efforts to promote cashless payments should go hand in hand with expanding financial access among underserved groups and regions, particularly agricultural and rural areas, remote and mountainous regions, islands, low-income groups, small and medium-sized enterprises, household businesses and other vulnerable groups. Financial products and delivery channels should be simple, convenient, affordable and tailored to actual customer needs.
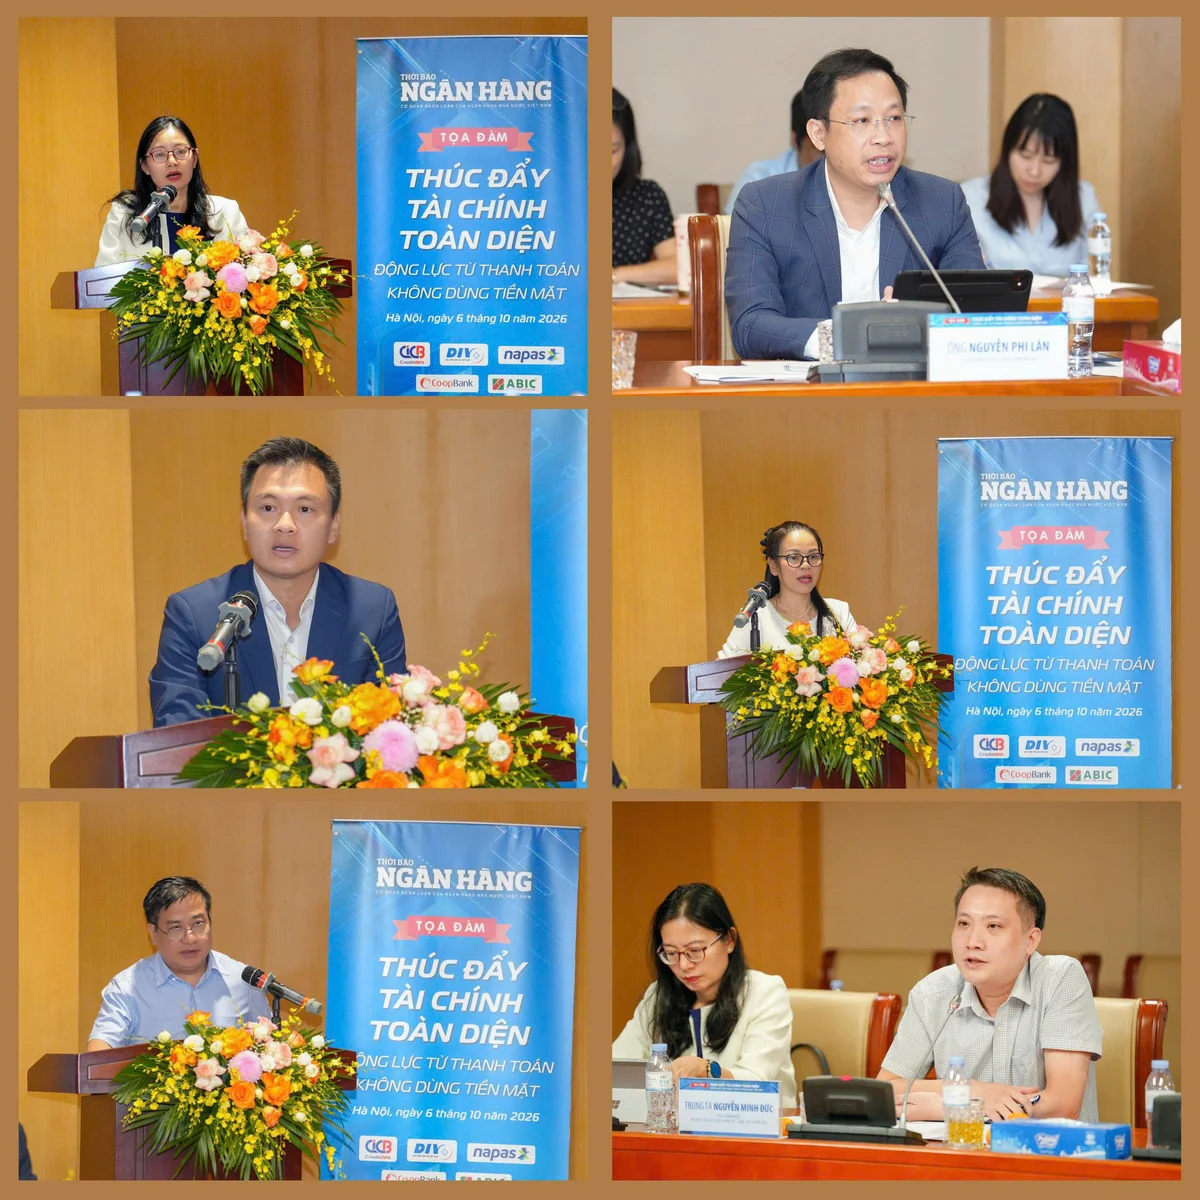
Speakers at the seminar
Safety and consumer protection at the core
Deputy Governor Pham Thanh Ha emphasized that safety, security, data protection and consumer protection must remain at the center of the digital transformation process.
“Rapid development must go hand in hand with sustainable development; innovation must be accompanied by risk management; and convenience must go hand in hand with safety and responsibility,” he noted.
He also called for continued efforts to promote financial education, improve citizens’ and businesses’ digital skills and awareness, and strengthen public communication to encourage safe and effective use of digital financial services.
“These are important factors in ensuring that digital payments are used regularly, fostering new financial habits and creating a foundation for the sustainable development of financial inclusion,” Deputy Governor Ha stressed.
Digital payments expanding financial access
The latest figures demonstrate the rapid expansion of cashless payments in Vietnam. As of August 2026, the value of cashless payment transactions was equivalent to 28 times national GDP, while 88.96% of adults held payment accounts.
The banking system has also made significant progress in strengthening customer-data security. Biometric data have been cleaned and matched for 174.5 million individual customer records and 2.92 million institutional customer records. Risk-prevention systems have issued warnings to 5.6 million customers, while 1.9 million transactions were suspended or cancelled, helping protect a total of approximately VND 6.3 trillion.
The reach of digital financial services is also expanding in rural areas and among vulnerable groups. As of June 30, 2026, there were approximately 5,700 payment-agent outlets operated by other organizations, while 11.45 million mobile-money accounts had been registered, of which 54% were active. There were also 5,158 mobile-money business points at the commune level.
QR codes and mobile phones are increasingly serving as payment acceptance points, helping overcome geographical barriers and bringing financial services to communities across the country at relatively low cost.
Building a foundation for sustainable financial inclusion
The development of cashless payments is therefore extending beyond the modernization of payment methods. It is increasingly becoming an important instrument for financial inclusion, enabling more people and businesses to access formal financial services while improving convenience, security and affordability.
Going forward, the challenge will be to ensure that the rapid expansion of digital payments is accompanied by robust infrastructure, effective risk management, strong consumer and data protection, and greater digital financial literacy. A balanced approach—combining innovation, accessibility, security and responsibility—will be essential to ensure that cashless payments contribute effectively to the sustainable development of financial inclusion in Vietnam.
VNBA News